
AI Quant Portfolio
Systematic portfolio driven by continuous research, strategy development, and disciplined portfolio management
REVO Capital constructs the AI Quant Portfolio by combining selected systematic strategies and continuously reviewing their composition and weights. Powered by AI Quant Forge, our AI-native research process develops, tests, and validates new strategy candidates, while portfolio construction focuses on achieving an attractive balance of return, risk, and diversification across the portfolio.
Our research process is designed to identify and evaluate a broad range of systematic alpha sources across markets, horizons, and strategy types. This allows us to construct portfolios around different investment objectives, including return targets, risk budgets, diversification needs, liquidity constraints, and correlation objectives.
Depending on the mandate, selected strategies from our research pipeline can be combined into customized systematic portfolios tailored to specific institutional requirements.
For questions about the portfolio, research process, or customized institutional solutions.
Current Portfolio Structure
The portfolio is constructed from a broader universe of strategy candidates. Selection considers how strategies interact, their underlying exposures, implementation costs, and portfolio-level constraints. Portfolio weights are reviewed as part of the ongoing investment process.
The research pipeline continuously develops and evaluates new candidates, while portfolio changes follow a separate review and rebalancing process.
Instruments and markets
US-listed equities and ETFs
- Markets
- United States
- Universe
- Largest 200 to 1,500 US-listed stocks, plus sector, asset-class and Treasury ETF baskets
- Long-only, long/short and market-neutral implementations
- Signals from daily data and, for selected strategies, intraday data
- Options and futures may be used as signal inputs; portfolio positions are held in cash equities and ETFs
Strategy candidate universe
Strategy categories considered for portfolio selection; actual composition changes through the review and rebalancing process.
Momentum
Cross-sectional, earnings- and fundamentals-driven, and multi-timeframe momentum
Fundamental Factors
Quality, value, dividend-growth and cash-flow signals
Event-Driven
Earnings, analyst revisions and news sentiment
Mean Reversion
Short-term reversals in single stocks and index ETFs
Macro and Regime Rotation
Sector and asset rotation conditioned on growth, inflation, yield-curve and volatility regimes
Trend Following
Single-ETF and multi-asset trend signals
Risk Overlays
Tail-risk hedging, volatility scaling and downside-risk control
Individual strategies, signals and positions are not disclosed. Portfolio composition may change through the review and rebalancing process.

AI-Native Research Pipeline
Quantitative research has traditionally been constrained by the researcher time required to review new work, translate it into testable hypotheses, implement strategies, and evaluate their robustness. Our AI-native research framework transforms this funnel into a continuous workflow, with structured validation and human oversight at each stage.
Portfolio construction is a distinct step in the process: candidates that pass testing are evaluated for how they fit together, and portfolio weights are determined within applicable constraints before implementation.
1.Research
Identify testable investment hypotheses from quantitative research and internal work.
2.DevelopValidate
Translate ideas into systematic trading rules and evaluate candidates through backtesting, modeled trading costs, and robustness testing.
3.SelectAllocate
Select strategies based on portfolio fit and determine weights within risk and implementation constraints.
Portfolio composition and target weights are determined here, before implementation.
4.MonitorReview
Track implementation and portfolio behavior, and review candidates for future rebalancing.
AI Quant Forge
Public window into our AI-native research process
AI Quant Forge showcases selected outputs of our research process, including systematic strategy case studies, research methodology, Paper Radar, and a forward paper model portfolio. The site also provides visibility into how strategies are tested and evaluated, including implementation assumptions, limitations, transaction costs, and the separation of historical backtests from forward results.
The paper portfolio is a research model with hypothetical results and is presented separately from actual fund and client-account performance.
The Team
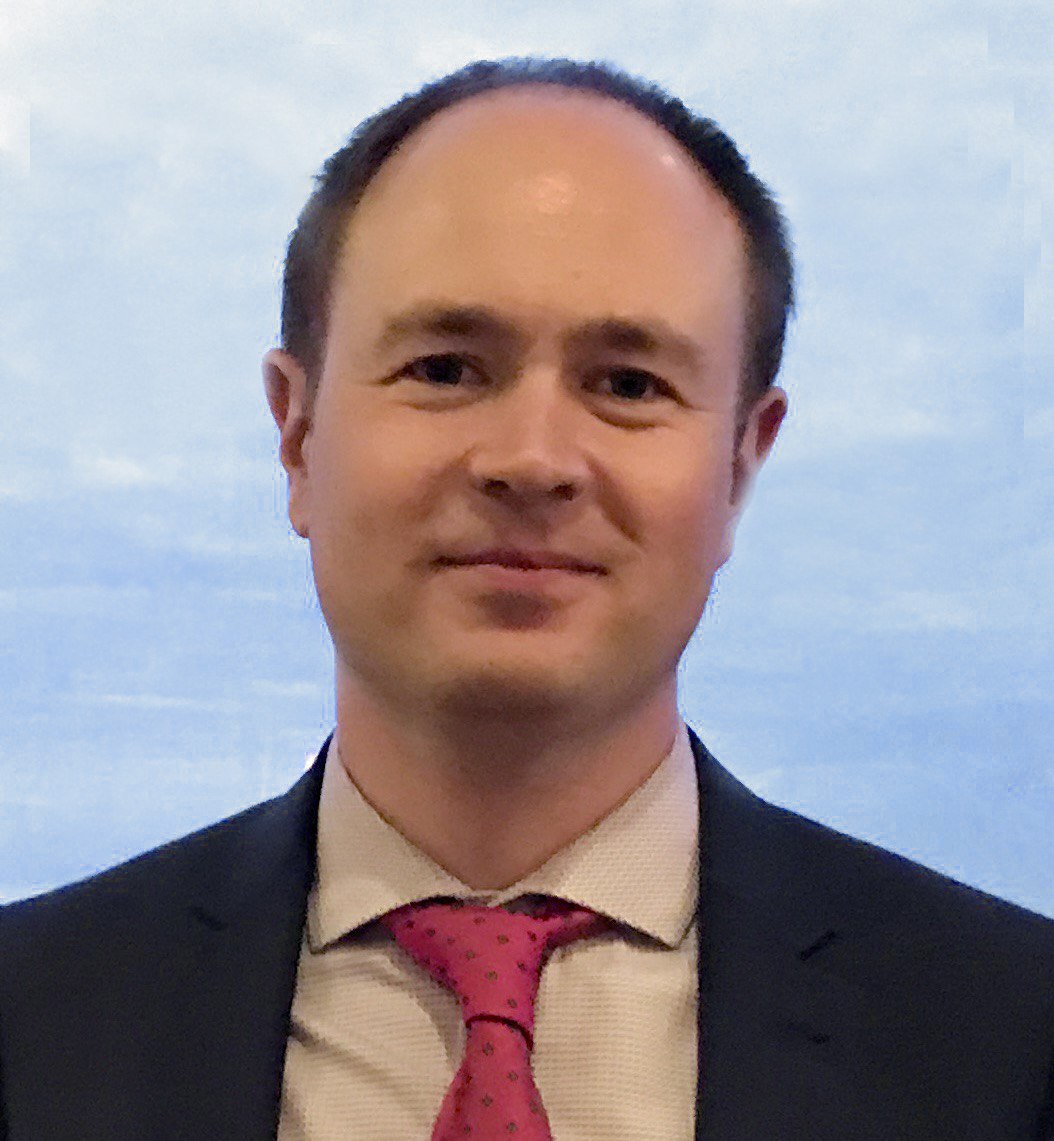
Vladimir Ofitserov, CFA
Managing Partner
Vladimir co-leads the investment process and oversees operations at REVO Capital, working closely with investment professionals to understand their objectives and develop tailored solutions.
LinkedIn(opens in a new tab)Eugene Reznikov
Partner & Head of Quantitative Research
Eugene leads research at REVO Capital across the full strategy lifecycle, from development and validation to portfolio construction. He also drives the integration of AI-native capabilities across the research process, including the AI Quant Forge research platform.
LinkedIn(opens in a new tab)

Collaborate With Us
We work with investment firms and allocators seeking new sources of alpha, portfolio enhancements, and systematic implementation without the need to build substantial in-house research and execution capabilities.
Engagements can range from targeted alpha research and strategy evaluation to end-to-end development and automated execution. Contact our team to start a discussion.
Contact Us
Questions about the AI Quant Portfolio, research capabilities, customized solutions, or potential collaboration. We will reply to you by email.